A seller-financed mortgage can work well for years, until the person receiving the payments needs cash now or no longer wants to manage the loan. At that point, a common question is: does note sale affect borrower? Usually, the borrower’s core obligation stays the same. They still owe the remaining balance under the signed note and security instrument, but they may begin making payments to a new Continue Reading about Does Note Sale Affect Borrower? What Changes
Uncategorized
How Retirees Sell Payment Streams for Cash

A monthly payment from a buyer can feel reassuring when retirement begins. But when that payment is tied to a seller-financed property sale, it also makes you responsible for waiting, collecting, tracking, and managing risk. Understanding how retirees sell payment streams can help you decide whether turning future mortgage payments into cash now fits your plans. For many retired note holders, the Continue Reading about How Retirees Sell Payment Streams for Cash
Loan Servicing Transition Guide for Note Holders
A seller-financed note can feel simple while payments arrive on time: receive the check, apply it to the balance, and keep the records. The process becomes more consequential when the note is sold, inherited, or assigned to a professional servicer. This loan servicing transition guide explains how to handle that change with clear records, respectful borrower communication, and fewer opportunities Continue Reading about Loan Servicing Transition Guide for Note Holders
Best Uses for Lump Sum Cash From a Note Sale
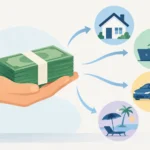
A seller-financed mortgage note can provide dependable monthly income, but the money may arrive too slowly for what you need now. After selling all or part of a note, choosing the best uses for lump sum cash is about more than spending it wisely. It is an opportunity to reduce financial pressure, strengthen your position, and put your money to work on your own timetable. The right choice depends Continue Reading about Best Uses for Lump Sum Cash From a Note Sale
Cash Settlement Versus Installments Compared
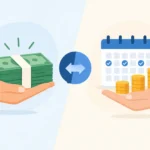
A seller-financed note can look very different after a few years of collecting payments. What once provided dependable monthly income may now feel like a responsibility you would rather leave behind. When weighing cash settlement versus installments, the real question is not simply which option pays more on paper. It is which option better supports your finances, time, and peace of mind now. For Continue Reading about Cash Settlement Versus Installments Compared
Common Borrower Payment Issues and What to Do
A seller-financed sale can work well for both sides until the monthly payment stops arriving as expected. Common borrower payment issues often begin quietly: a payment arrives a few days late, a check is short, or a borrower asks to skip one month because of a temporary setback. For a private note holder, these are not just small administrative inconveniences. They can affect cash flow, create Continue Reading about Common Borrower Payment Issues and What to Do
When Should I Sell Payments From My Mortgage Note?
A seller-financed property sale can feel like a smart arrangement at closing. You receive a down payment, earn interest, and collect monthly income rather than waiting for one lump sum. But circumstances change. If you are asking, when should I sell payments from my mortgage note, the most useful answer is not tied to a single date on the calendar. It is tied to whether those future payments still Continue Reading about When Should I Sell Payments From My Mortgage Note?
Evaluating Cash Settlement Offers for Notes
A seller-financed note can look very different a few years after the property sale. What once provided dependable monthly income may now feel like a delay, an administrative responsibility, or a source of uncertainty. Evaluating cash settlement offers gives you a way to decide whether converting future mortgage payments into a lump sum supports your current financial priorities. The right offer is Continue Reading about Evaluating Cash Settlement Offers for Notes